


ICAI UDIN Portal Update: Important Changes for Tax Audit Assignments
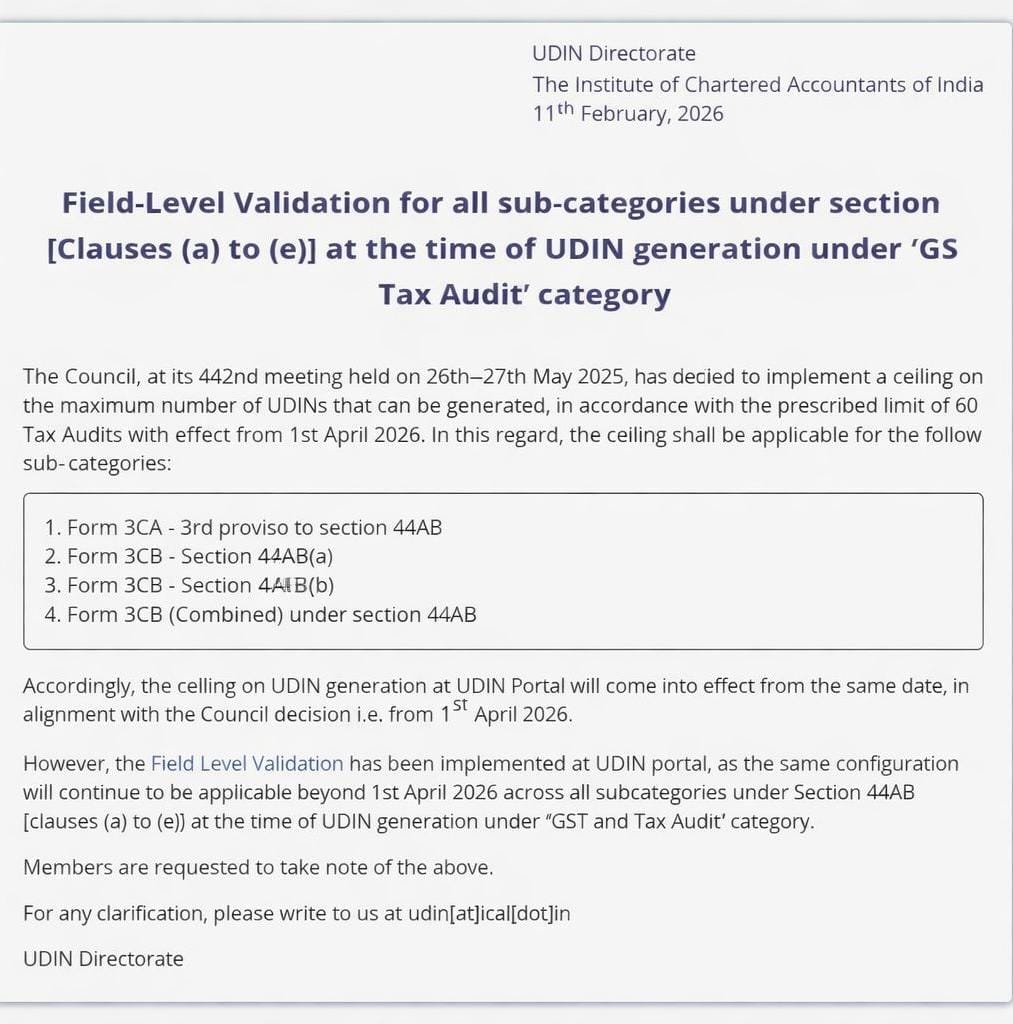
The Institute of Chartered Accountants of India has introduced important updates in the UDIN portal related to tax audit reports. If you are handling audits under Section 44AB, this update directly impacts your work.
Let us understand the changes in simple terms.
1. Clause Selection Under Section 44AB Is Now Strictly Validated
While generating UDIN under the GST & Tax Audit category, members must carefully select the correct clause of Section 44AB.
- 44AB(a)
- 44AB(b)
- 44AB(c)
- 44AB(d)
- 44AB(e)
The portal now includes field-level validation. This means incorrect clause selection or mismatched details may lead to rejection or future verification issues.
Members must ensure correct turnover details, audit type, and applicable clause are selected while generating UDIN.
2. 60 Tax Audit UDIN Limit Per Partner From 1 April 2026
ICAI has introduced a ceiling of 60 Tax Audit UDINs per partner effective from 1 April 2026.
This limit applies to:
- Form 3CA
- Form 3CB under Section 44AB(a)
- Form 3CB under Section 44AB(b)
- Form 3CB (Combined)
The restriction is applicable partner-wise, not firm-wise. Each partner can generate only 60 Tax Audit UDINs.
Firms must properly distribute audit assignments among partners to avoid last-minute compliance pressure during audit season.
Why This Update Matters
These changes are introduced to improve monitoring, transparency, and accuracy in tax audit reporting.
- Plan audit workload in advance
- Track number of assignments partner-wise
- Double-check clause selection before UDIN generation
Proper planning and accurate data entry will help avoid rejection, portal errors, and compliance issues during peak audit season.


0 Discussion Comments
No comments yet
Be the first to share your thoughts on this article.